Planning to invest in SIP? Follow these 5 simple steps

Most people think they need to have a lot of money before they can start investing. These days, with as little as Rs 500 you can get your feet wet with mutual funds.

Investing in SIP mutual funds allows you to take part in a larger pool of funds that will be managed by a professional fund manager. This presents a lot of advantages, the best of which is that you do not need to come up with a large sum to be able to invest in a variety of investment funds—say equities or bonds.

Mutual funds are also suitable for those who may not have the time and capacity to manage their own portfolio. Unlike directly investing in stocks or bonds which require you to devote time into managing your holdings, investing in a mutual fund with financial services companies somewhat frees you from these responsibilities.

If you think mutual funds are for you, here’s a step-by-step process to starting an SIP today:

Step 1: Intermediaries v/s Asset Management Companies (AMC)

First decide if you want to invest through intermediaries (banks, financial advisor) or directly via an AMC. Intermediaries are certified financial planners who will help you to select right funds according to your need, goal and time frame with proper asset allocation. Besides this, they will help with filling and submitting the forms and documents; hence they include a nominal fee.

If you have the expertise and knowledge in selecting mutual funds in India and the bandwidth to devote sufficient time and attention to the various aspects of investment management, you can consider investing in direct plans with the AMCs.

Step 2: Complete the KYC Procedure (Know your customer)

You need to be KYC compliant to begin investment in mutual fund. KYC is a one-time exercise that must be done if you want to invest. It can be done electronically through eKYCor by visiting the nearest KYC center in your city. Most fund houses have started providing this facility through their website. For KYC procedure, following documents are required – Identity proof, address proof and a passport size photograph.

Step 3: Find the right fund for SIP

As per your goal, time horizon, risk appetite, chose the right fund for SIP.

Equity (High Return, High Risk): Invest primarily in shares of stock Debt (Low Return, Low Risk): Invest in debt instruments of governments or corporations Balanced (Middle Ground): Invest both in shares of stock and debt instruments

Step 4: Decide the SIP amount

You need to calculate and decide how much you need to invest through SIPs to meet your various financial goals after considering expenses. It is advisable to give realistic time to your investments to achieve your goals with proper asset allocation and adjust the goal amount for inflation.

Step 5: Decide date, payment details and submit form

Once you choose the fund to begin SIP mutual fund decide whether you want a weekly, monthly or a quarterly investment plan. Choose a date on which the SIP amount will be directly debited from your bank account. One can also opt to make the make the payment through manual transfer or postdated cheques. After filing in all the details, submit the form. Thereafter, once the formalities are complete and SIP is registered, the AMC will send you the statements periodically.

Conclusion: An SIP can be the first of many investment instruments that can help you get started with planning your finances. These simple steps could eventually help you build a comfortable future for yourself and your family.
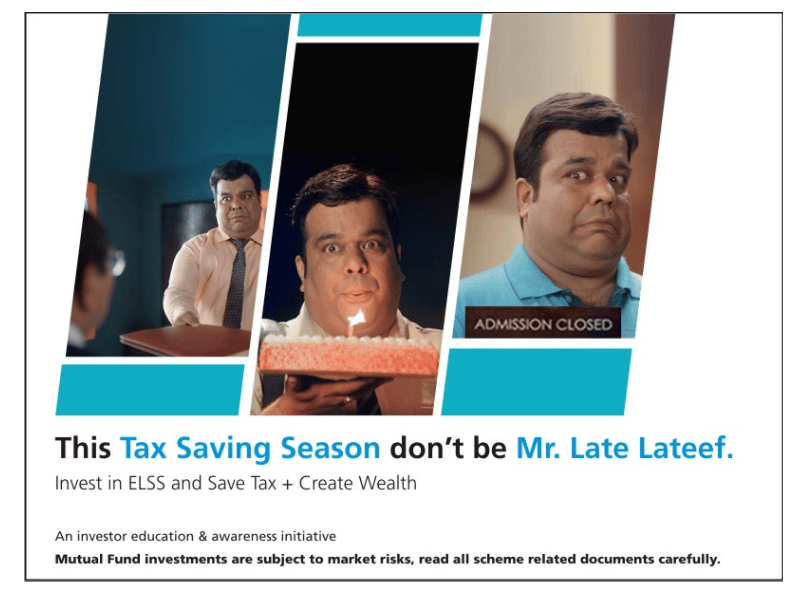
When it comes to saving tax, don’t be Mr. Late Lateef

It’s in our human nature to procrastinate – be it for want of something better or simply because of our hesitation in taking a decision. Like Mr. Late Lateef, we often tend to put things off until the last minute, which could be beneficial in some situations in our attempt to achieve perfection, but most often it backfires!
 
Procrastination makes us miss all the good opportunities as you can see in our latest film. And each one of these could have a snowballing effect over the long term. So the wisest choice would be to follow the idiom, “Don’t do tomorrow what you can do today”.
 
The same it also true when it comes to saving tax. Our last-minute tax saving decisions could lead to the wrong investment decisions being made! How so? The answer is easy. We often go by the advice of our friends and family and hurriedly choose a traditional investment options presented by them without considering other options or realising the suitability of the product for us

L&T Mutual Fund has launched an integrated digital campaign called ‘‘Late Lateef” that reiterates the importance of early planning in ELSS for not only tax saving but also wealth creation. The idea of the campaign is to connect with the masses through the portrayal of the universal habit of procrastination in everyday life and the snowball effects of delaying important tasks.

A quirky, new aged 30 seconds rap-based montage film, Late Lateef, uses everyday scenarios to connect with the audience. The film revolves around Mr. Late Lateef, who procrastinates important tasks like school admission for his daughter or birthday wishes for his wife until the last minute that puts him in a difficult position. The film, with four different scenarios is made humorous by expressions of the characters and music. The film, advises Mr. Late Lateef not to be late for tax saving and to create wealth through investments in ELSS.

Equity Linked Savings Scheme (ELSS):

Now is the time to consider Equity Linked Savings Scheme (ELSS) – an investment with a lock-in period of three years that can also help you to create wealth! By investing in the growth potential of equities, ELSS helps you save up to Rs. 46,800* under Section 80C^ of the Income Tax Act while also giving your money the opportunity to grow and build wealth over the long term!

*^The tax saving shown has been calculated for a person aged less than 60 years in the highest income tax slab having annual income less than Rs. 50 lakhs, as per Section 80C of the Income Tax Act, 1961 for the Financial Year 2019-20 and includes applicable cess. We have considered the current 4% educational cess on tax. Including cess, the tax saving per annum would amount to 31.2% of Rs. 1.5 Lakh or Rs. 46,800.

An Investor Education & Awareness Initiative

CLICK HERE TO KNOW MORE

Disclaimer – This document is for general information only and does not have regard to specific investment objectives, financial situation and the particular needs of any specific person who may receive this information. This document provides general information on performance; financial planning and/or comparisons made are only for illustration purposes. The data/information used/disclosed in this document is only for information purposes and not guaranteeing / indicating any returns. Investments in MFs and secondary markets inherently involve risks and recipient should consult their legal, tax and financial advisors before investing. Recipient should also understand that any reference to the indices/ sectors/ securities/ schemes etc. in the document is only for illustration purpose and should not be considered as recommendation(s) from the author or L&T Investment Management Limited, the asset management company of L&T Mutual Fund or any of its associates. Recipient of this information should understand that statements made herein regarding future prospects may not be realized or achieved. The distribution of this document in certain jurisdictions may be restricted or totally prohibited and accordingly, persons who come into possession of this document are required to inform themselves about, and to observe, any such restrictions.

Mutual Fund investments are subject to market risks, read all scheme related documents carefully.

Source: Times Of India

Timing The Markets – No Worries With SIP

It might be tempting to try to time the market, but the illustration above shows it’s just not worth it to play that game. Studies have shown that a regular investor makes more money than the one who times the market. The best way to make such investments is through an SIP or Systematic Investment Plan which can help reduce the risk of timing the market by averaging out benefits.

Investing in equities through mutual fund is one of the feasible ways to build a solid corpus. And since mutual funds are managed by experienced fund managers, one does not have to bother too much about what choices to make and where to invest.

Over a period of time, returns from an SIP in mutual funds will comfortably exceed inflation. In fact, an SIP-based approach can be considered as a good way to beat volatility as SIP is usually low-risk when evaluated over a long period of time. In the end, remember that building wealth is a long-term commitment, and to do so, it is better to stick to an SIP rather than trying to time out the markets.

CLICK HERE TO KNOW MORE

An Investor Education Initiative

Disclaimer – This document is for general information only and does not have regard to specific investment objectives, financial situation and the particular needs of any specific person who may receive this information. This document provides general information on performance; financial planning and/or comparisons made are only for illustration purposes. The data/information used/disclosed in this document is only for information purposes and not guaranteeing / indicating any returns. Investments in MFs and secondary markets inherently involve risks and recipient should consult their legal, tax and financial advisors before investing. Recipient should also understand that any reference to the indices/ sectors/ securities/ schemes etc. in the document is only for illustration purpose and should not be considered as recommendation(s) from the author or L&T Investment Management Limited, the asset management company of L&T Mutual Fund or any of its associates. Recipient of this information should understand that statements made herein regarding future prospects may not be realized or achieved. The distribution of this document in certain jurisdictions may be restricted or totally prohibited and accordingly, persons who come into possession of this document are required to inform themselves about, and to observe, any such restrictions.

Mutual Fund investments are subject to market risks, read all scheme related documents carefully.   

Source: Economic Times

Different Avenues of Tax Saving

Tax planning is no child’s play. For the same reason, you could consider engaging a financial adviser who would guide you through the entire process, choosing the tax saving instrument, investing, and then monitoring the performance to make sure you do not go astray. 

By composing the right mix of investments for your portfolio, you can exempt more of your income from tax and ensure that you are receiving optimal returns. Section 80C of the Income Tax Act offers a broad range of options, each suited to a different need. However, an Equity Linked Savings Scheme (ELSS) or tax saving mutual fund schemes provide investors tax benefits combined with long-term wealth creation through equity exposure and comes with the shortest lock-in among all tax-saving instruments. 

Your Tax Saver

Towards the end of the financial year, most of us start chalking out our tax plans, or the lack of one. If you are a salaried professional, you might get a reminder from your accounts department and if you are self-employed, your accountant would remind you to ‘do your taxes’. Either way, it ends up being at the eleventh hour.

While some of us may have done the smart thing by planning early, the majority might have not.

However, this is merely a ‘tax saving’ exercise and cannot be called ‘tax-planning’. Tax planning is all about planning in advance, which involves evaluating your overall tax strategy and implementing it before the year-end.

In this way, you can make the most out of your tax saving opportunities, which would eventually help you accumulate wealth over the long-term. Tax Planning is an essential part of financial planning and deserves the rightful time and effort.

So when we think about tax-saving as a goal, various options come to mind, that qualify under deduction under Section 80C of the Income Tax Act, 1961, which allows deduction up to Rs. 1,50,000. The options available under Section 80C are as follows:

1. Market Linked

– Equity Linked Savings Scheme (ELSS)

– Unit Linked Insurance Plan (ULIP)

– Nation Pension Scheme (NPS)

2. Fixed Income

– Public Provident Fund (PPF)

– National Savings Certificate (NSC)

– Tax Saving FDs

– Senior Citizen Saving Scheme (SCSS)

– Employee Provident Fund 

– NABARD Bonds

3. Others

– Life Insurance Premium

– Repayment of house loan (Principal)

– Children’s Tuition Fees

The answer however varies, from person to person, objective to objective, and as per the risk appetite. 

With the above tax saving instruments available, the obvious question that arises in our minds is, which option should I opt for? Should I select one of above or should I invest some chunk of money into all or some of the above to claim the deduction? Well, the answer for this question is skewed as every individual has different set of requirements and risk appetite. However, it’s critical, not to just look at the tax saving criteria of the avenue under consideration, but also it’s potential to generate higher returns.

CLICK HERE TO KNOW MORE

An Investor Education Initiative

Disclaimer – This document is for general information only and does not have regard to specific investment objectives, financial situation and the particular needs of any specific person who may receive this information. This document provides general information on performance; financial planning and/or comparisons made are only for illustration purposes. The data/information used/disclosed in this document is only for information purposes and not guaranteeing / indicating any returns. Investments in MFs and secondary markets inherently involve risks and recipient should consult their legal, tax and financial advisors before investing. Recipient should also understand that any reference to the indices/ sectors/ securities/ schemes etc. in the document is only for illustration purpose and should not be considered as recommendation(s) from the author or L&T Investment Management Limited, the asset management company of L&T Mutual Fund or any of its associates. Recipient of this information should understand that statements made herein regarding future prospects may not be realized or achieved. The distribution of this document in certain jurisdictions may be restricted or totally prohibited and accordingly, persons who come into possession of this document are required to inform themselves about, and to observe, any such restrictions. 

Mutual Fund investments are subject to market risks, read all scheme related documents carefully.

Source: Times Of India

Quick Guide on Income Tax

Tax! It’s such a little word. But the best of us find it terrifying. Perhaps it’s because we know so little about it. While we fulfil out tax obligation every year, we also owe it to ourselves to make the most of tax savings and create real wealth for the future.

Your tax bracket

It is but obvious that everyone who earns income has to pay tax. But how much – that is the questions that your tax bracket answers. Your ‘taxable income’ or ‘Income after deduction’ defines your tax bracket.

There are three categories of individual taxpayers:

1. Individuals (below the age of 60 years) which includes residents as well as non-residents:

  • Income up to 2.5 Lakh – No Tax
  • Income from 2.5 Lakh to 5 Lakh – 5%
  • Income from 5 Lakh to 10 Lakh – 20%
  • Income more than 10 Lakh – 30%

2. Resident Senior citizens (60 years and above but below 80 years of age)

  • Income up to 3 Lakh – No Tax
  • Income from 3 Lakh to 5 Lakh – 5%
  • Income from 5 Lakh to 10 Lakh – 20%
  • Income more than 10 Lakh – 30%

3. Resident Super senior citizens (above 80 years of age)

  • Income up to 5 Lakh – No Tax
  • Income from 5 Lakh to 10 Lakh – 20%
  • Income more than 10 Lakh – 30%
  • @4% Health and Education Cess for individuals in the Tax
  • Surcharge: 10% of income tax, where total income exceeds Rs 50 lakh up to Rs 1 crore.
  • Surcharge: 15% of income tax, where the total income exceeds Rs 1 crore to Rs 2 crore
  • Surcharge : 25% of income tax, where the total income exceeds Rs 2 crore to Rs 5 crore
  • Surcharge : 37% of income tax, where the total income exceeds Rs 5 crore
  • Rebate under section 87A: The rebate is available to a resident individual if his total income does not exceed Rs 5 lakh. The amount of rebate shall be 100% of income tax or Rs 12,500 whichever is less.

Determine your tax-saving instrument

While Section 80C of the Income Tax Act offers you a range of options for tax saving such as Equity Linked Saving Scheme, Public Provident Fund (PPF), National Pension Scheme and National Savings Certificate (NSC) etc., your choice must depend on your income, risk appetite and return expectations.

Life insurance basically safeguards you against risk, except for Unit Linked Insurance Plans, which invest a part of the money into markets and the other part is dedicated to insurance, which does not earn any return. Fixed rate interest bearing instruments such as PPF and NSC are better suited for risk averse investors since they are backed by the government or by established financial institutions. However, they may not be able to beat inflation in the long term.

An ELSS, however, is a pure equity option, which invests in the stock market and provides capital gains over the long term.

A mantra that precedes every investment plan – start early. Most investors start the hunt for tax saving instruments during the end of the financial year, when the fear of tax hits them. Investments in tax saving instruments demand attention and research. Starting early can help you make better choices, save tax more efficiently and capitalize on the investment returns. In order to minimize the anxiety associated with the time of tax filing and avoid surprises, adding a financial advisor could be beneficial.

An Investor Education Initiative

Disclaimer – This document is for general information only and does not have regard to specific investment objectives, financial situation and the particular needs of any specific person who may receive this information. This document provides general information on performance; financial planning and/or comparisons made are only for illustration purposes. The data/information used/disclosed in this document is only for information purposes and not guaranteeing / indicating any returns. Investments in mutual funds and secondary markets inherently involve risks and recipient should consult their legal, tax and financial advisors before investing. Recipient should also understand that any reference to the indices/ sectors/ securities/ schemes etc. in the document is only for illustration purpose and should not be considered as recommendation(s) from the author or L&T Investment Management Limited, the asset management company of L&T Mutual Fund or any of its associates. Recipient of this information should understand that statements made herein regarding future prospects may not be realized or achieved. The distribution of this document in certain jurisdictions may be restricted or totally prohibited and accordingly, persons who come into possession of this document are required to inform themselves about, and to observe, any such restrictions.

Mutual Fund investments are subject to market risks, read all scheme related documents carefully.

Source: Times Of India

Design a site like this with WordPress.com
Get started